

Buying a Second Home at The Cliffs
Buying a second home is a considered decision, and treating it that way from the outset changes the outcome. Financing works differently than for a primary residence; tax treatment depends on how the home is used, and a purchase across state lines brings its own set of questions. The reasons for wanting one vary: a change of pace, a home built for gathering, a trial run at future retirement; the process of getting there looks the same.
This guide moves through those decisions in the order a buyer typically faces them: getting financially ready, deciding how the home will be used, choosing a market, weighing in-state against out-of-state, budgeting for what ownership actually costs. Throughout, it draws on what these decisions look like in practice at The Cliffs, where members have been navigating them for decades.
Step 1: Get Financially Ready
Cash or Financed
Many second-home buyers can pay cash outright and still choose to finance, a decision less about affordability and more about where capital is best put to work. A mortgage keeps funds liquid and invested elsewhere rather than concentrated in a single property, and the after-tax cost of borrowing often compares favorably to what that capital would otherwise return. Others prefer the simplicity and negotiating position a cash offer provides. The right approach depends on the broader financial picture, and that’s a conversation to have with a wealth advisor before the search begins, not after the right property is found.
What Lenders Look For
- Down payment: A minimum of 10% for a second home with strong credit, though many lenders ask for 15 to 20%. Jumbo loans, common at this price point, often call for 20 to 25% or more.
- Credit score: Generally the high 600s or better.
- Debt-to-income ratio: A combined ratio, across both mortgages, under roughly 43 to 45%.
- Cash reserves: Two to six months of combined mortgage payments in liquid savings remaining after closing.
- Rate: Typically a quarter to half a percentage point above primary residence rates, with jumbo loans carrying a slightly wider margin.
A pre-approval, arranged before touring properties, sets a clear budget and clarifies which loan structure, or whether financing makes sense at all, fits the purchase.
Step 2: Decide How You’ll Use It
Second Home or Investment Property
Many second-home owners at The Cliffs never rent the property, and that simplicity is part of the appeal: no tenants, no scheduling, and no shift in insurance or tax treatment. For those who do intend regular rental income, the property is classified differently. A second home is one occupied for a meaningful part of the year; an investment property is one purchased primarily to generate income. Lenders determine the category based on stated intent, and each has its own down payment minimum, rate, and documentation.
How That Choice Plays Out at Tax Time
For an owner who never rents the property, the picture is straightforward: mortgage interest is generally deductible on up to $750,000 in combined mortgage debt across a primary and second home, provided the owner itemizes. Property taxes fall under the state and local tax (SALT) deduction, which is capped, though that cap has been rising in recent years and phases out at higher income levels.
For those who do rent occasionally or regularly, the treatment shifts:
- Rented 14 days or fewer per year: That income isn’t reportable at all.
- Rented more than 14 days, but used personally more than that: The home stays classified as a residence, with rental income and proportional expenses reported accordingly.
- Rented more than it’s used personally: The home shifts to investment property status. Property taxes and mortgage interest become deductible as business expenses outside the SALT and $750,000 caps, and the structure itself can be depreciated over 27.5 years.
Step 3: Choose Your Market
Not every place beautiful in July holds up as a place to own.
- Year-round appeal. A location with something to offer across all four seasons protects both use frequency and the home’s long-term value.
- Real access. Proximity to a major airport, or a city with genuine culture and dining, keeps a property from becoming harder to reach than it’s worth.
- Privacy with programming. Gated and private communities offer discretion for a home that sits empty part of the year, paired with amenities that keep it feeling lived-in even when it isn’t.
- A track record. Consistent sales activity and price appreciation over time say more about a market’s staying power than any single standout listing
Build or Buy
Buyers who already know the view, the layout, and the lot tend to build, working with a builder to shape a home suited to exactly how they’ll use it. Buyers ready to move in on their own timeline tend to buy, often into newly built inventory already underway in active communities. Building or buying depends on how particular the vision is, and how soon it needs to become real.
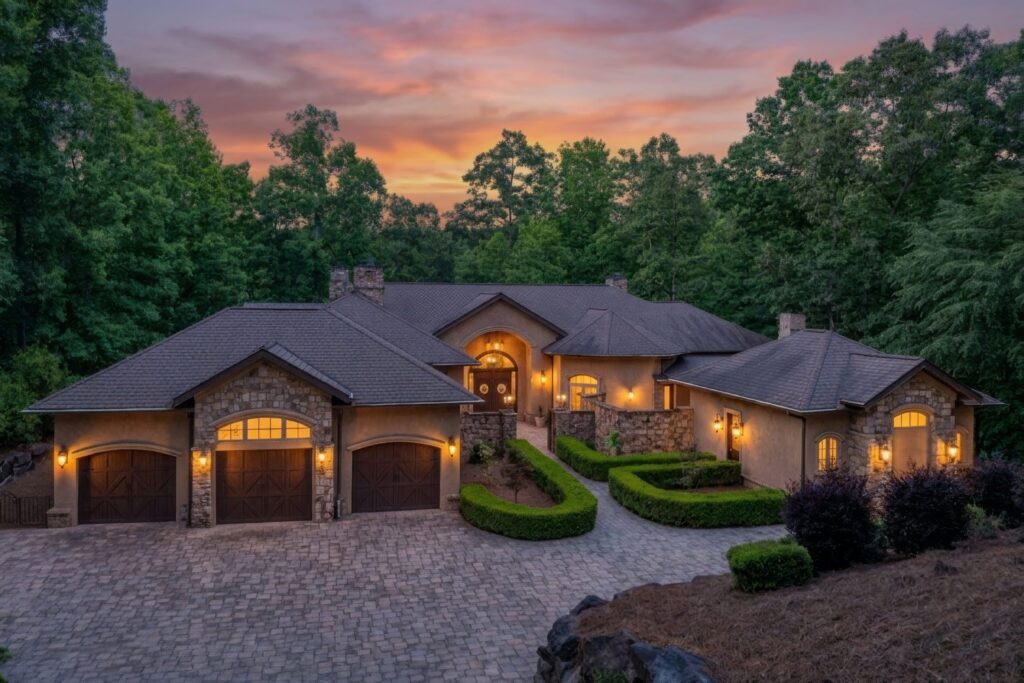
At The Cliffs, both paths stay active year-round. Move-in-ready estates, mountain retreats, and lakefront homes are available now through Cliffs Realty. Those who’d rather build can work with Preferred Builders on a fully custom home, or Cliffs Builders on a semi-custom package, with new homesite releases opening regularly across all seven communities.
Step 4: Decide In-State or Out
Ownership carries no residency requirement. The complexity of an out-of-state purchase is practical, not legal.
What Changes Across State Lines
- Property taxes vary meaningfully by county and state, both in rate and in how the property is assessed.
- Insurance has to be written new, not added to an existing policy, and should reflect the property’s specific location and risks, or shift to a landlord policy entirely if the property will be rented.
- Distance means maintenance and small issues need a local point of contact, whether that’s a property manager or someone trusted nearby.
- Closing can happen without ever stepping onto the property in person, with a local agent, inspector, and title company handling the details on the ground.
Step 5: Budget for the Cost Of Ownership
The mortgage payment is only part of what owning a second home actually costs. Consider the rest from the start, especially for a home that sits empty part of the year.
- Maintenance. A common rule of thumb is to set aside 1 to 2% of a home’s value annually for upkeep and repairs, and a second home often runs toward the higher end since small issues go unnoticed longer between visits.
- Insurance. Second home premiums typically run higher than a primary residence, often 20 to 30% more, since insurers price in the added risk of a property that isn’t occupied year-round.
- HOA or club dues. Community fees vary widely by location and amenities, and they tend to rise over time rather than hold steady, so it’s worth reviewing a few years of association budgets before buying rather than taking the current rate at face value.
- Utilities and upkeep while away. Heating, cooling, and basic monitoring still need to run when no one’s there, both for comfort on arrival and to protect the property against frozen pipes or unnoticed damage.
- Property management, if renting. Professional management typically runs 8 to 12% of rental income, a cost worth weighing against the time and distance involved in handling it independently.
Where This Comes Together: The Cliffs
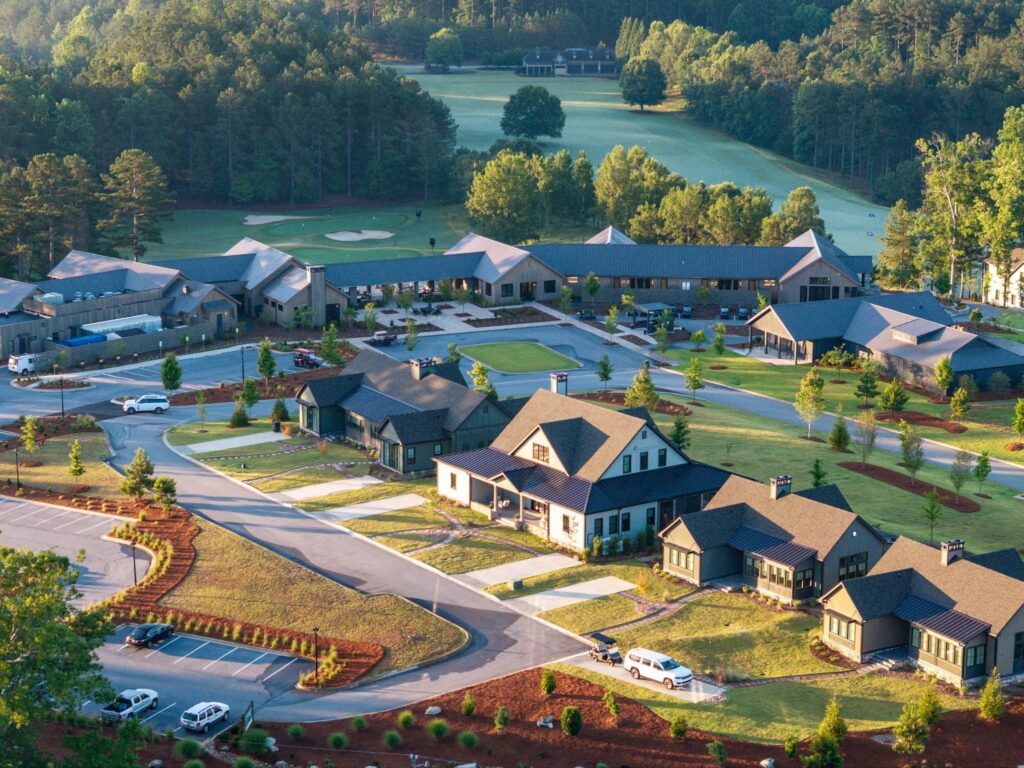
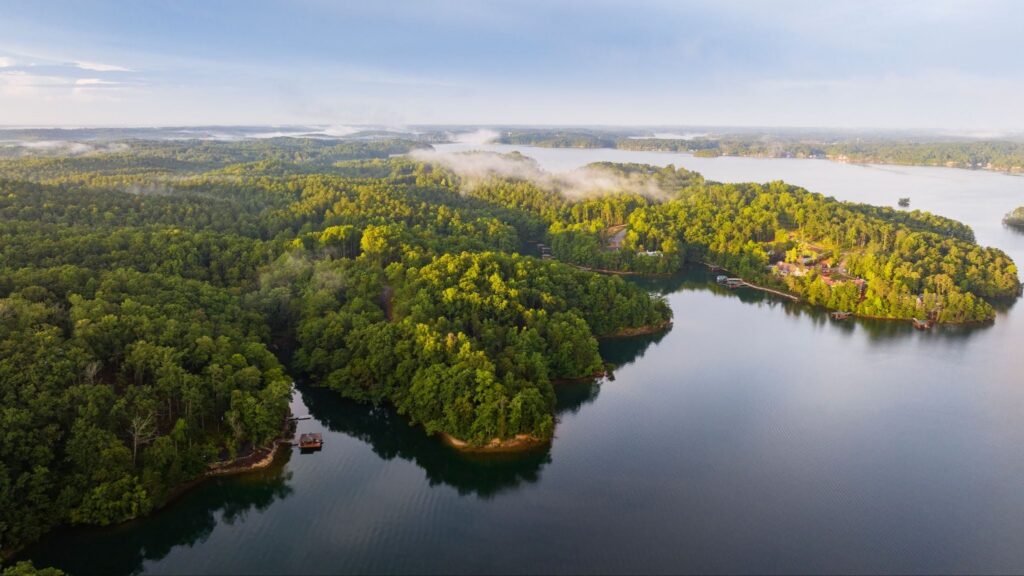
The Cliffs spans seven private communities across the Blue Ridge Mountains of North and South Carolina, from the mountains above Greenville, to the shores of Lake Keowee, to the hills outside Asheville. One Club Membership opens every community, so the choice isn’t a single neighborhood so much as an entire region: mountain golf communities, lakefront living on 300 miles of Lake Keowee shoreline, or a private club minutes from downtown Asheville.
That range solves a real problem for second-home buyers weighing one market against another. Rather than choose between a mountain property in one state and a lake property in another, members own in a single community and use the amenities—golf, wellness, dining—across all seven. For those who do want to open a home to guests occasionally, Cliffs Property Management offers a member-to-member rental arrangement across the South Carolina communities, an option outside the traditional rental market entirely.
The right community is the one that already feels like home.